The Knowledge Problem
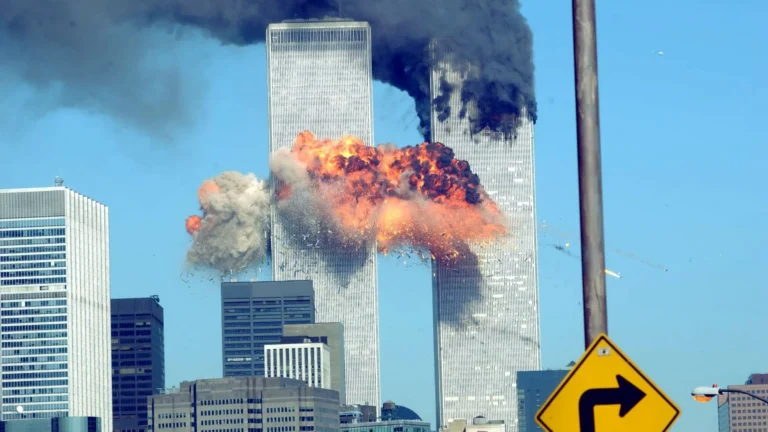
After 9/11 we chose safety over freedom
16 September 2026
Spencer Platt/Getty Images
If there was one event that ended Fukuyama’s ‘end of history’, it was 9/11. The growth and predominance of globalisation were followed by anti-Western intellectual movements. Many, especially on the Left, are still obsessed with rationalising the insanity of the attackers – most notoriously streamer Hasan Piker, who claimed in 2019 that ‘America deserved 9/11’. ‘They did it because they were poor!’ Osama bin Laden was the privileged son of a Saudi construction millionaire. ‘They did it because they were uneducated!’ Of the 19 hijackers, nearly three-quarters had higher education. The lead hijacker, Mohamed Atta, was studying for a PhD in Germany.
The wind of change that began in 1989 turned after 9/11. The dream of a globalised world in which everyone would live together was too good to be true from the start.
In the modern world, people do not lose their liberty through the invasion of an emperor from a neighbouring country, but through the subtle surrender of their own freedom in exchange for a little more safety
Tony Blair said at the 1997 NATO-Russia summit in Paris: ‘Mine is the first generation able to contemplate the possibility that we may live our entire lives without going to war or sending our children to war.’ Then came the War on Terror. Not only was the dissolution of the Soviet Union not the end of history; it opened the door to many questions for which we were unprepared. The world was not witnessing the convergence of all other models towards liberal democracy. As the anthropologist Clifford Geertz observed, the post-Cold War world had to confront two central questions: ‘What is a country if it is not a nation?’ and ‘What is a culture if it is not a consensus?’
That change was not limited to culture and foreign policy. It affected economics as well. In the immediate aftermath of the September 11, 2001 attacks, the yield on 10-year US Treasury bonds stood at 4.68% on September 14. By September 2026, the 10-year Treasury yield was breaking 5%. A borrowing cost unseen in nearly two decades has effectively become the new normal for the US government, even in peacetime.
The same trend can be seen around the world. Italy now has a debt-to-GDP ratio of 138.9%, while France has gross debt of €3.4 trillion. High borrowing costs do not seem to have restrained governments’ appetite for further borrowing. As we have seen in Britain, what was considered a crisis during Liz Truss’s premiership has become the new normal. Governments and voters have become accustomed to high borrowing costs.
How did the world get used to them? A poll found that people in developing countries are more open to AI than those in developed countries. Strange? Not when you look at the labour market. If you own a small shop in Indonesia, there may not be much to lose from AI. It could even help you manage your accounts, hire fewer people and reduce your costs. But imagine that you are a worker in the United States, with a mortgage and a stable job. You have much more to lose if AI replaces what you do.
This seems to be a broader trend: the more prosperous societies become, the more risk-averse they become. This was what Tocqueville saw. In the modern world, people do not lose their liberty through the invasion of an emperor from a neighbouring country, but through the subtle surrender of their own freedom in exchange for a little more safety.
Tocqueville wrote that people could give away so much of their agency that ‘they can do almost nothing by themselves’. The rise of the modern welfare state has created a hyper-protective society, in which 25% of adults in this country think they are disabled. Someone has to pay for the safety nets, and that someone is often the risk-taker who gets punished.
But when a protective society wants both low taxes and more spending, debt seems the best choice for politicians. It was not long ago that Gordon Brown wanted to introduce a fiscal rule under which debt-to-GDP would remain below 40%. Now it is close to 95%.
By going into debt, governments can provide the benefits of spending today while leaving someone else to pay for it tomorrow. But that arrangement does not last forever. Eventually, governments hit the limit, and high borrowing costs enter the equation.
Ferguson’s Law says that great powers can get into trouble when the cost of servicing their debt begins to crowd out the spending needed to maintain their power. Britain now pays 3.5% of GDP in debt-interest payments – more than the defence-spending target to which nobody knows whether Healey remains committed.
As debt-service costs rise, the political pressure to find an easy way out inevitably grows. The clear case is JD Vance, the vice-president of the United States. He believes that the dollar’s status as the global reserve currency acts as a ‘massive tax on American producers’ and harms the US industrial base.
This is Vance’s subtle way to open the discussion about devaluing the dollar to reduce the real burden of the debt. But it is clear that Vance does not understand that once you try to pay your debt by devaluing your currency, even your own citizens may lose trust in that debt. Look at Argentina.
What is problematic about the high-debt, high-spending trend that took hold after 2008 is not simply that it is unsustainable, or that it must eventually result in a crash. It is that this has become the new normal, and that those who now want to solve the problem are often the same people who spent years arguing that governments which increased debt-to-GDP from around 40% to 95% were practising ‘austerity’.
You could almost hear the revolutionary vitriol dripping onto the Labour benches during Monday night’s Lords debate on political donations, following the announcement of Reform’s £72 million bonanza from two crypto billionaires with UK voting rights but recent residence abroad. ‘An undermining of democracy and rampant Americanisation’, one peeress spat out. A case of ‘the […]
Did you ever hear the one about the leaders of Sinn Fein, Plaid Cymru and the Scottish National Party holding a press conference? It sounds like the beginning of a bad joke, but yesterday, the UK’s foremost regional separatists came together in Cardiff to pressure Andy Burnham into facilitating the dissolution of the nation. Michelle […]
If rumours are to be believed, Kemi Badenoch and the Conservative Party are thinking about scrapping inheritance tax. Inheritance tax is a pernicious tax that punishes people for doing things that we are supposed to do: building things, saving and investing. Crucially, it is also a tax on loving your family and wanting to leave […]