I particularly enjoy a phrase that appears in Christopher Bullock’s ‘The Cobbler of Preston’: ‘Tis impossible to be sure of any thing but Death and Taxes.’ The sentiment was later popularised by Benjamin Franklin in his correspondence. In the world of government budgets, there’s another thing that is, sooner or later, unavoidable: fiscal consolidation. That means closing the gap between what a government spends and what it raises, so that it borrows less each year.
Governments are particularly good at expanding the scope of spending to a point where they accumulate large stocks of national debt and large amounts of yearly borrowing. Higher interest rates on that debt add to the pressure: in the UK, debt interest already takes about £1 in every £12 the government spends.
Whatever the governing party, managing interest groups and political loyalties becomes harder when there is less money to go round and a general sense of crisis
Most countries that experience debt problems struggle to implement lasting fiscal consolidation. Governments tend to hope that growth will do the work for them, lifting tax receipts without anyone having to vote for higher taxes or lower spending. When it doesn’t, the options narrow to raising taxes, cutting spending or both.
Raising taxes can hit growth, making the problem worse, and rolling back spending is a particularly thorny issue. Whatever the governing party, managing interest groups and political loyalties becomes harder when there is less money to go round and a general sense of crisis.
After the global financial crisis of 2008, many Eastern European countries found themselves in the unenviable position of still playing catch-up. Following the fall of the Iron Curtain, they had transitioned to market economies and spent years rebuilding the institutions needed to sustain them. However, those countries soon discovered that rapid catch-up growth could coexist with fragile public finances. In many countries such as Romania, tax collection remained weak and the informal economy was substantial, making it hard to stabilise a growing deficit.
This means that a country can get into trouble even if its overall debt is relatively low. In Romania, annual borrowing needs were acute, with a budget deficit of roughly 9% of GDP in 2009, following a rapid expansion of spending commitments. Between 2005 and 2008, nominal spending on public wages and pensions nearly doubled.
As borrowing from foreign markets became difficult, Romania turned to an international rescue package in 2009. In May 2010, its then-president, Traian Băsescu, announced a sweeping fiscal consolidation programme, including cuts to public-sector pay of 25% and pensions of 15%. This was accompanied by raising VAT from 19% to 24% to boost revenues and complement the imposed spending cuts.
The budget deficit fell from 9% of GDP in 2009 to 2.9% in 2012. The following year, the European Union closed Romania’s excessive-deficit procedure.
Despite returning public finances to a healthy state, the government faced a brutal political reckoning. Prime Minister Emil Boc resigned in February 2012 after protests. His successor fell in a confidence vote that April. In December, the alliance led by Boc’s Democratic Liberal Party won just 16.5% of the lower-house vote, against 32.4% for the party alone in 2008.
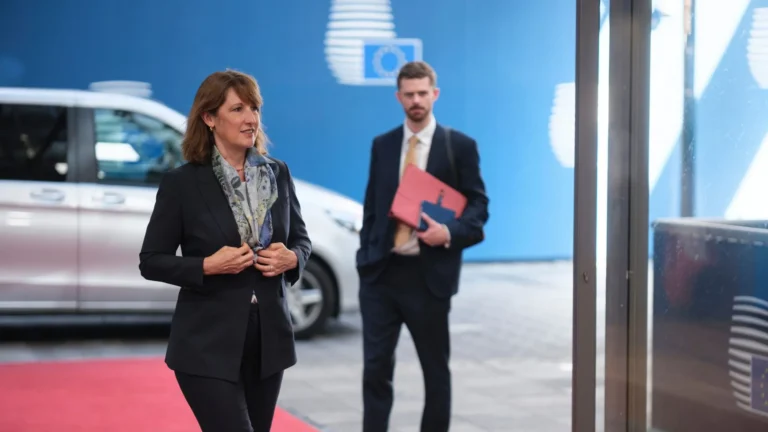
It is hard to say what the right programme looks like, or whether it can be sold to the public without a harsh political penalty. In many Western countries, especially Britain, even mild attempts at fiscal consolidation meet fierce criticism. Rachel Reeves’s attempt to make a modest cut to the welfare bill by restricting the Winter Fuel Allowance payments provoked a backlash and was substantially reversed in 2025. That hardly bodes well for either further consolidation or the government’s electoral prospects.
Stay informed with our free daily briefing.
Perhaps one day Britain will find its own Democratic Liberal Party, ready to light its own funeral pyre in the name of fixing the public finances and laying the foundations for stronger economic growth. Given the lack of appetite for spending political capital even on small things, it is hard to be more than ever so mildly hopeful.
What is worse is that if no one wants to make hard decisions and risk dying a hero, then whoever is forced to manage a more painful fiscal reckoning down the line will surely go down as a villain.
Just as there is a battle on the Right in Britain, so too is there a battle inside the Conservative Party for what the party should focus on. There are those who are concerned about the threat of political Islam, the damage to the social fabric of the Boriswave and other elements of mass immigration, […]
07 Oct 2026
Conservatives
Mani Basharzad
Badenoch’s inheritance tax pledge is a battle cry
When William Buckley went on the front page of Time magazine, the title was simple: ‘Conservatism Can Be Fun’. That is what Kemi Badenoch has done at this conference. Conservatism can be fun, can be serious and can learn from its old mistakes. But most importantly, what makes it the world’s oldest party is its […]
06 Oct 2026
Trade
Ben Ramanauskas
Don’t tariff Chinese cars
It has been reported that the UK looks set to follow the example of the EU in imposing tariffs on electric vehicles from China. This would be a mistake, for five main reasons. First, we have to look at the main reason why the UK is considering doing it. The EU is using its proposed […]
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes.The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.