Healey’s tax raid on banks is bad for growth
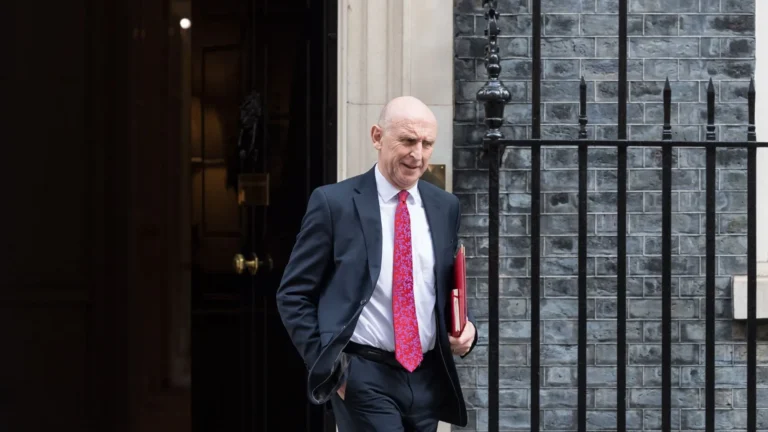
Wiktor Szymanowicz/Future Publishing via Getty Images
Should banks be taxed more? That seems to be one of the routes that the Chancellor will go down in the Budget, according to news reports from Bangkok, where he is attending the annual meetings of the International Monetary Fund and World Bank.
Thousands of bankers will be in attendance and he is likely to be one of the only finance ministers sending such a message of another tax raid.
For an industry like banking that is globally competitive, and for a country like the UK that has the world’s second largest financial centre and the one with the largest number of banks, it is a brave decision to take.
The tax that looks set to be raised is the bank surcharge. This was cut from 8% to 3% in April 2023. The suggestion is to raise it back to 8%. Is it worth the hassle? Banks paid £1.2 billion in bank surcharge in 2025/26. A hike to 8% is estimated to raise around an additional £2.2 billion. The additional money is not insignificant but, for a Government raising over £1 trillion in tax, it is a small proportion. Yet raising it risks sending a clear signal that successful sectors are cash cows. That is not a good message to send.
Thousands of bankers will be in attendance and he (John Healey) is likely to be one of the only finance ministers sending such a message of another tax raid
In addition to the surcharge, banks pay corporation tax at 25%, which rose as the surcharge was cut. They also pay £1.4 billion a year through a bank levy, an annual tax levied on different components of their balance sheet. Then, on top of this, they pay the same taxes as others, such as National Insurance.
Roughly speaking, banks pay about one-tenth of corporation tax. UK Finance claims that their total tax contribution, including taxes borne by their workers, was £43.3 billion in 2024/25. This is already significant.
This higher tax policy would likely lead to banks passing on costs to consumers. It also speaks to not knowing how to encourage economic growth and to not taking the tough political decisions on controlling public spending.
While I am not a supporter of banks paying more tax, I am in favour of a shift in how much interest is paid to banks on their reserves at the Bank of England.
In ‘Breaking the Cycle’, I argued for the Bank of England to shift from paying Bank Rate on all bank reserves and instead move to a tiered system, which is used elsewhere. Although this would reduce how much banks receive, it is materially different to a levy on their balance sheets or a surcharge on their profits. It is more a case of reducing what is in effect a subsidy from the taxpayer to the banks, and one which looks set to increase if the Bank Rate rises. Paying Bank Rate on all reserves is a policy choice, not a necessity for monetary control or financial stability.
Moving to a tiered system could still allow effective monetary control over interest rates and save the Exchequer significant amounts; it could be over £10 billion, depending on the approach. This would be far more than would be raised by a higher bank surcharge.
While the Iran war this year triggered volatility in financial markets there was remarkable financial stability. This welcome development was in part because banks were well capitalised and liquid. This was a global, not just a UK phenomenon.
Banks’ profits and their ability to benefit from higher policy rates through wider net interest margins are feeding pressure for higher taxes. But their solid financial position merits a shift in the conversation, away from yet higher tax rates to whether the sector is pulling its weight in the UK economy. Given its strong capital and liquidity positions, should it be lending more?
There is another part of the equation, although this is not under the Chancellor’s remit: the argument to remove unnecessary capital burdens where evidence supports the case for doing so.
Easing unnecessary capital requirements, where justified, should lessen their cost of lending. This is not the only explanation for their lending behaviour but it might help.
Lower capital burdens are not, and should not be seen as, part of a bargaining process that compensates for higher taxes. The latter should be based on many fiscal factors and are set by the Chancellor. In contrast, capital requirements are determined by risk and financial stability issues and fall under the regulators.
There are international norms that the UK helped set and which will stay. It is the unnecessary or excessive requirements that might be reduced. One example to examine is the countercyclical capital buffer, set by the Financial Policy Committee. It is 2%. In Germany it is 0.75%. In France it is 1%. It is extra capital required to be held against relevant risk-weighted assets. These comparisons warrant scrutiny, although differences in the wider capital frameworks also matter.
Banks should lend more. The financing gap facing smaller businesses was identified in 1931 by the Macmillan Committee. It has remained a perennial issue. This March, the British Business Bank pointed out that challenger and specialist banks account for 60% of gross bank lending to small and medium-sized enterprises (SME), up from 39% in 2012. That would imply £41 billion out of £68 billion. In contrast, the share of the big five banks was only £27 billion, or 40%.
Meanwhile, the latest lending data from August highlights that the annual growth rate of lending to large firms from banks and building societies continues to outstrip that to SMEs, at 8.9% against 4.6%. The rate charged on new loans to SMEs is also far higher, at 6.63% compared with 5.57% for non-financial companies overall. Differences in risk and the cost of providing smaller loans might explain this. Even so, the message is that SME bank lending is growing more slowly and is more costly. The aim should be to encourage banks to increase their lending to this sector.
There is a need to ensure that the City is internationally competitive and also serves the best interests of the UK economy. The approach to banks is central to that. There are many moving parts: taxation, reserve remuneration, capital requirements and the supply and cost of lending. They need to be considered together, not in isolation. As with many aspects of the UK economy, higher taxes are not the right answer.
The remarkable thing about Britain’s tax burden is that however high it rises, the government always manages to spend more than it can afford, and John Healey’s first Budget looks unlikely to be any different. Businesses are expected to swallow higher taxes, workers are expected to give up more of their earnings and anyone lucky […]
The IMF has just published its biannual World Economic Outlook. The report appeared to be modestly good news for the UK, predicting higher-than-expected economic growth of 1.3% in 2026, up from a 1% forecast in July. But one thing that caught my eye was the way that the IMF reported that the UK would see […]
For the past 10 years, the European Centre for Entrepreneurship and Policy Reform (ECEPR) has been mapping Europe’s knowledge-intensive jobs in a recurring study, with a particular focus on how the geography of knowledge is shifting. The 2026 index shows the UK ahead compared to other large nations in Europe, but also reveals that smaller […]