Corporate welfare is Britain’s blind spot
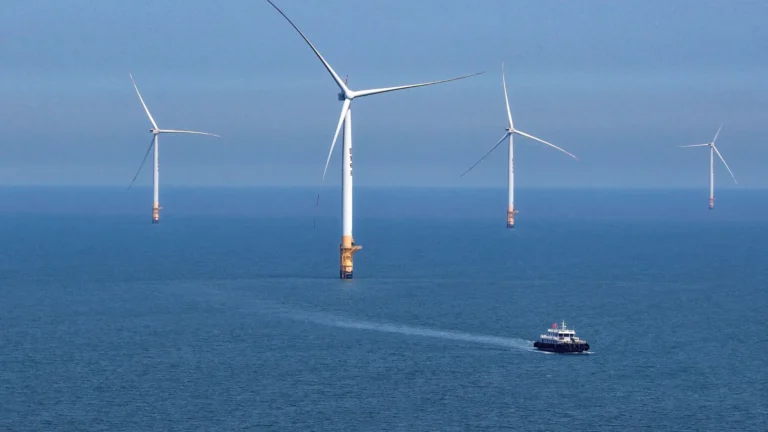
Support for offshore wind is hard to count – Yang Bo/China News Service/VCG via Getty Images
Britain’s political class loves to talk about ‘reforming welfare’, but everyone knows the limits of that ambition. Voter Welfare – the £333.7 billion the state is forecast to transfer from taxpayers to households in 2025–26 – is politically untouchable. A population brought up on free cake is unlikely to vote for the plate being removed, at least until it stares a debt tragedy square in the face.
But there is another kind of welfare that receives far less attention and may actually be fixable: Rent-Seeking Welfare, or what is more bluntly called corporate welfare elsewhere. Unlike pensioners, corporations don’t vote – and British households don’t own many shares directly. In theory, this should make reform easier. In practice, the obstacle is not ideology but something more basic: the Government cannot see what it is trying to reform.
You cannot reform what you cannot measure, and Britain cannot presently measure corporate welfare in any meaningful way
The UK does not possess a coherent account of how much support business receives, who receives it, through which channels or what any of it achieves. Support is scattered across subsidies, grants, tax reliefs, loans, guarantees, equity injections, nationalisations, procurement rules and regulated returns. These are recorded on different bases, by different departments, and often without a common identifier for the final beneficiary.
The National Audit Office has been unusually blunt about this. In 2020 it concluded that ‘most schemes in our review lacked measurable objectives from the outset or evaluations of their impact to know if they are providing the most value or if they should be discontinued’. In its review of growth-oriented tax measures, the NAO found ‘too many examples where these reliefs either do not achieve their economic objectives or are subject to significant error and fraud, costing the Exchequer billions of pounds’. Meanwhile a joint costing project run by the Treasury and BEIS, using figures from 2016-17, found that government held recipient data for only 16% of business-support cost across the schemes examined.
This is a collection of poorly connected favours, not an investment strategy.
Even the official subsidy number – the ONS’s ‘transaction D.3’ category, running at around £36bn a year – is misleading. It excludes tax expenditures, preferential tax treatments, loans, guarantees, capital grants, public procurement, regulated returns and local-authority support. Add those in and the true figure is far higher. There is no requirement to count it, so nobody knows by how much.
The electricity system is a perfect illustration of the problem. Governments give grants to wind-farm supply chains. They also enter into Contracts for Difference that guarantee revenues to generators. The cost of those contracts is passed through to electricity bills. The Government then subsidises selected households to offset the costs its own scheme created. Energy-intensive manufacturers are exempted from some of these costs; other businesses are not. Low-carbon generators enjoy revenue certainty, except when wholesale prices exceed contract prices, at which point the payments reverse.
Is this a subsidy? A tax? A regulatory privilege? A consumer levy? A business exemption? All of them.
A non-exhaustive list of overlapping schemes – the Warm Home Discount, the Boiler Upgrade Scheme, Renewables Obligation support, energy-intensive-industry exemptions, network-charging compensation and the British Industry Supercharger – reveals a system in which costs are shuffled between taxpayers, billpayers, households and firms with no clear sense of purpose or outcome. The largest support to wind generators is not a grant at all, but Contract for Difference revenue support financed through electricity bills. The largest support to energy-intensive manufacturers, meanwhile, is exemption from costs that other businesses must still pay.
Tax reliefs are no better. R&D tax reliefs are set to cost around £8bn in 2025–26. Creative-industry reliefs cost £2.4bn in the latest published year. The Patent Box costs £2.3bn, with large companies – just 28% of claimants – taking 95% of the relief. Business Asset Disposal Relief is forecast to cost £800 million in 2025–26, though the cost spiked to £3.4bn in 2024–25 as disposals were brought forward ahead of a rate rise – and in any case it benefits owners selling businesses rather than the businesses themselves. These measures may or may not be economically justified. The point is that government does not know, because it does not evaluate them as a portfolio.
This is why reforming Rent-Seeking Welfare is harder than it looks. Politically, it should be simple: voters are not emotionally attached to corporate subsidies. Technically, it is a mess. You cannot reform what you cannot measure, and Britain cannot presently measure corporate welfare in any meaningful way.
The starting point for reform is not abolition or expansion, but visibility. Before ministers announce new initiatives – or defend old ones – government should be required to publish a common account of each support measure: the recipient, the instrument, the annual fiscal cost, other support received, the stated purpose and the evidence of additionality. Without that, Britain will continue to operate a system in which nobody can say with confidence how much support a particular business, sector or region receives – or whether the taxpayer obtains anything resembling a return.
Voter Welfare may be politically untouchable. Rent-Seeking Welfare should not be. But until Britain stops administering corporate support as a fog of overlapping schemes, exemptions and tax breaks, reform will remain a theoretical ambition. The first task is not to cut corporate welfare or to defend it, but to count it.
So, this week financial markets started pricing four or even five Bank of England rate rises over the next year. On the evidence in front of me today, that is lunacy. In fact, I called it rubbish on GB News yesterday lunchtime. Against that backdrop, the Federal Reserve raised its key interest rate by 25 […]
You could almost hear the revolutionary vitriol dripping onto the Labour benches during Monday night’s Lords debate on political donations, following the announcement of Reform’s £72 million bonanza from two crypto billionaires with UK voting rights but recent residence abroad. ‘An undermining of democracy and rampant Americanisation’, one peeress spat out. A case of ‘the […]
If there was one event that ended Fukuyama’s ‘end of history’, it was 9/11. The growth and predominance of globalisation were followed by anti-Western intellectual movements. Many, especially on the Left, are still obsessed with rationalising the insanity of the attackers – most notoriously streamer Hasan Piker, who claimed in 2019 that ‘America deserved 9/11’. […]