How socialist is Reform’s Poundland plan?
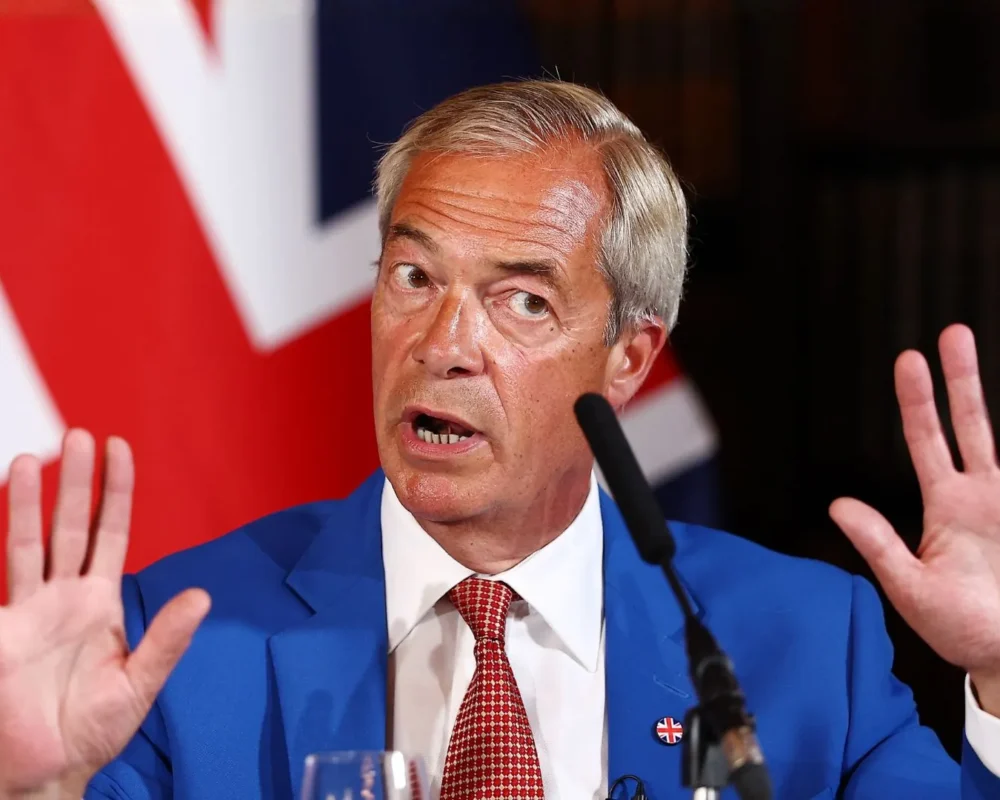
Dan Kitwood/Getty Images
I’ll declare an interest. I sit on Reform UK’s Board and I’ve known Nigel Farage for a quarter of a century. So when Kemi Badenoch tells the country that Reform are ‘another left-wing party’, that we and Labour are arguing for ‘the same things, nationalisation, the two-child benefit cap’, that Farage is Jeremy Corbyn wrapped in a Union Jack, I’m not a neutral witness. I am, though, a witness.
Her charge, admittedly, does have evidence behind it. Exhibit A is Scunthorpe in April 2025, when Farage stood at the gates of British Steel and said the furnaces should be taken into public ownership. ‘I don’t think Richard and I are natural people to say let’s nationalise things,’ he told the local paper, ‘but this is urgent.’ Two blast furnaces, 2,700 jobs, and a G20 economy days from becoming the only one on the planet unable to make primary steel. The Labour Government agreed. Shortly afterwards, Keir Starmer recalled Parliament and seized control of the firm, paving the way for nationalisation this summer.
Where Jenrick is open to the charge is his tone. ‘Wall Street’ is a leftist trope for demonising free markets. Bernie Sanders loves it
Nor was Scunthorpe a sudden change of direction. On the Today programme in January 2014, Farage said he’d rather we weren’t ‘slightly richer’ if the price of staying in the EU was 5 million more people, because the social side of the question mattered more than pure market economics. He has always had a laissez-faire gut and an empirical head. The gut says leave people alone. The head says a nation is more than a spreadsheet, and that some things, steel among them, you don’t let the market decide.
Now the Tories have a new exhibit. Poundland.
Steve Smith opened the first Poundland in Burton-upon-Trent in 1990 with £50,000. By the time Pepco sold it, Poundland had 825 shops and 16,000 staff. In June 2025 Pepco, its Polish-listed owner, sold the lot to Gordon Brothers, a Boston restructuring house, for £1. Gordon Brothers also picked up a £30 million shareholder loan that doesn’t mature until 2030. Remember that.
What followed was a court-approved restructuring. Dozens of shops closed, two of four distribution centres went, and about 2,200 jobs with them. Last year sales fell 12% and the business lost roughly £1m a week. That’s not a Tory talking point, whatever Reform’s Treasury spokesman Robert Jenrick told Fraser Nelson on Sunday: it’s in the accounts. But the turnaround seemed to be working. Management told suppliers that September sales rose 6.7% like for like, the first three weeks of October 8.4% and margins were running ahead of plan. Management had a buyer. Martin Property Group (MPG), a Northern Irish family firm, made what management called a fully funded, solvent offer for the whole business, 600 shops, the Irish Dealz chain, 12,000 jobs saved.
Gordon Brothers said no. The sticking point was the £30m loan.
The Americans wanted it repaid in full, instantly. MPG offered half up front with the rest deferred. On October 29, the day after John Healey’s first Budget, Poundland filed a notice of intention to appoint administrators. Gordon Brothers would now rather sell around half the shops piecemeal to B&M, Poundstretcher, The Range and others, while letting the rest hang.
How was a chain serving 6 million customers a week losing a million pounds a week? Partly its own doing. It filled the shelves with Pepco’s Polish clothing and lost its DNA. Temu and Amazon ate what was left. But the state also had its hand in the till.
Rachel Reeves’s 2024 Budget lifted employer National Insurance from 13.8% to 15% and dropped the threshold at which it bites from £9,100 to £5,000. A shop assistant working 12 hours a week used to cost her employer nothing in National Insurance (NI). Now she costs 15% of everything over £96 a week. The living wage also went from £11.44 to £12.21 to £12.71. Poundland, like most of the high street, runs on part-time hours, and last year it already put the combined hit from the NI and minimum wage changes at around £30m. Last week, Healey added another 3.9% to the minimum wage for next April. Poundland’s margins were already pennies. The Government has been squeezing them even further.
‘12,000 jobs at Poundland are on the line,’ Jenrick posted on October 30. ‘Wall Street shouldn’t be allowed to destroy a major British business to satisfy their investors. Burnham needs to act.’ He has asked the Government to facilitate a sale to another buyer.
Is that left-wing? He hasn’t asked for a penny of public money. The Prime Minister Andy Burnham, who has 270 of those jobs at a distribution centre in his own Makerfield constituency, has himself written to Boston demanding to know why the bids were refused. Jenrick is similarly asking that a refusal of a willing, solvent buyer be looked at when the seller’s motive appears to be liquidation, when the sale would cost the taxpayer nothing and the collapse would cost it up to 12,000 redundancies before Christmas. That isn’t Clause Four. It’s the question Theresa May was asking about Cadbury and AstraZeneca when she wanted the Tory leadership.
Fraser Nelson’s counter is the natural free-market objection. Capitalism requires both profit and loss to work. Stop bankruptcy, and you keep zombies alive and frighten off the capital that funds the next Steve Smith. Hound moneylenders and they go elsewhere. All true. Also true that Gordon Brothers is a liquidator as much as a lender, and one that bought a loan for a pound and now wants 30 million for it in a hurry. It is about to smother Poundland’s turnaround, despite being brought in to deliver it.
Where Jenrick is open to the charge is his tone. ‘Wall Street’ is a leftist trope for demonising free markets. Bernie Sanders loves it.
Now read the Economic Rescue Plan Jenrick published the day before the Budget. Sixty-four measures. The personal allowance increased to £15,000, lifting 2.9 million people out of income tax at a cost of £17.7 billion, paid for by £40 billion of cuts, £20 billion of it from welfare, £8 billion from Net Zero subsidies, £6 billion from aid. Employer National Insurance back to 13.8% for British workers. The VAT registration threshold to £150,000. No income tax on overtime under £75,000. Approve Rosebank, restart North Sea licensing, scrap the windfall tax that Jenrick says is driving the rigs to Norway. Build nuclear the French and Korean way, fast and cheap. Cut capital gains tax on crypto.
Badenoch’s own pamphlet, ‘The Right Way’, admits the Tories spent 14 years administering New Labour’s machinery rather than dismantling it. She’ll find most of the dismantling she never did in our Teal Paper. If this is socialism, Thatcher was a Trot.
But Reform are not a party of the Mont Pelerin catechism. Reform would nationalise the last blast furnace. Reform think the social side matters more than pure market economics, and that was a Tory position long before it was a Labour one. Disraeli invented it. Even Salisbury kept a version of it. So did Macmillan, until his party was taught to be embarrassed.
The Tories’ problem isn’t that Reform are left-wing. It’s that Reform have remembered what conservatism is for.
You could almost hear the revolutionary vitriol dripping onto the Labour benches during Monday night’s Lords debate on political donations, following the announcement of Reform’s £72 million bonanza from two crypto billionaires with UK voting rights but recent residence abroad. ‘An undermining of democracy and rampant Americanisation’, one peeress spat out. A case of ‘the […]
The verdict is clear. The Right has woken up to the innate statism associated with a statutory Net Zero target. Reform UK reject it outright, and the Conservatives have pledged to scrap the 2050 deadline and the 2008 Climate Change Act by which net-zero targets are enforced. Both accept the approach is a millstone around […]
The last time I wrote about Reform UK’s annual conference I was doing it as the Deputy Editor of this fine publication. A year on, how much has changed? Greeting you as you enter the conference hall is the familiar fare for the familiar fee. Chicken and chips stands sit next to anti-Labour propaganda, accompanied […]