It’s time for Britain to fix its broken budgets
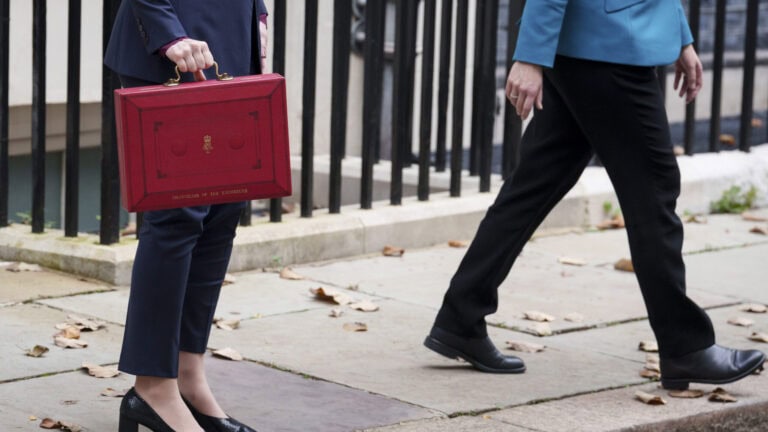
Photo: Richard Baker / In Pictures via Getty Images
While it’s almost certain that Rachel Reeves will meet her fiscal rules at this week’s Budget, her rules will not stop the UK’s slide to bankruptcy. In case you haven’t been on the rollercoaster of economic speculation, Rachel Reeves has three fiscal rules. The first of these is that the current Budget must be in surplus in four years’ time, according to forecasts from the Office for Budget Responsibility (OBR). The second is that public sector net financial liabilities, as a percentage of GDP, must be falling. The third is a cap on some forms of welfare spending.
We know these rules will fail to improve Britain’s finances because they have failed for almost 30 years, regardless of whether there was a Conservative or Labour chancellor in charge. This is ironic, given that Gordon Brown introduced the concept of fiscal rules to ‘ensure an historic break from the short-termism and expediency’.
But the clear evidence is that fiscal rules have not moved us from short-termism. The UK has not run a surplus since Gordon Brown was chancellor. Public sector net debt has risen from less than 40% of GDP to almost 100%. Furthermore, the overall health of the Government’s balance sheet and long-term pressures on health and pensions have not been addressed.
In a report for the Centre for Policy Studies, I suggest there are five reasons why the rules are inadequate. The first is that the rules encourage deficit bias. In theory, governments should balance spending over the business cycle – run deficits in downturns but run a surplus on the other side to pay off debt. The problem is that, while chancellors are happy to borrow when there is a downturn, they always spend the upside when economic times are better.
The second reason is that hard decisions are put off. Fiscal policy is kept loose in the next one to two years, with promised restraint by the target date. Of course, in a couple of years’ time, that restraint is never exercised. While looking at the OBR’s forecast database, which contains forecasts going back to 1990, we found that the government always spent more than it forecast it would in the final year of the forecast. Actual spending was on average 3.5% of GDP higher than forecast (the equivalent of roughly £100 billion today) if you exclude the pandemic years, or 4.7% of GDP including Covid.
The third reason is that policy is designed specifically to meet the fiscal rules. We witnessed this in April with the welfare policies that were designed purely to meet fiscal rules, rather than drive fundamental welfare reform.
The fourth reason is that the rules are based on spurious precision, where we are obsessing about £10 billion in four years’ time. In the context of a Budget that could be worth almost £1.5 trillion, this is pocket change. Yet the entire debate hinges on this precise number. But analysis of OBR forecasts shows massive changes between what is forecast and what actually happens, not because the OBR is bad at forecasting, but because forecasting ahead is complicated. That’s not to say we shouldn’t look ahead (the next point argues looking even further forward), but that we shouldn’t rely on such artificial precision.
The final reason is that the fiscal framework fails to deal with the major long-term pressures facing the UK. It ignores many non-debt liabilities (the largest being public sector pensions), and massive spending pressures for future generations.
It’s easy to say that the UK has faced big shocks in the past 25 years – the financial crisis, Brexit and the Covid pandemic. But many other countries have faced crises in the same time and come out stronger. It may be uncomfortable to acknowledge, but the UK has had spendthrift governments that have wasted the reasonably strong fiscal position it had in 2000.
What can we do about it? In the report, I suggest two things. The first is that chancellors should be forced to look at a much wider range of measures of financial health. That means looking not only at deficits, but also the full set of government liabilities and future spending patterns. That means budgets can be a debate about how we leave a more financially secure country for our children, while balancing what we need to spend today.
The second is more accountability for decisions already made. No chancellor has had to report back on whether what was promised actually came true. Other countries have much stronger enforcement mechanisms: in Switzerland for example, the government must balance its budget throughout the economic cycle. Past indiscretions must be accounted for and paid for by future governments.
Getting the precise settings right will be a challenge. That’s because prudent fiscal management is about more than just rules and frameworks. It’s about a political culture that sees fiscal excess as unacceptable. A fiscal framework should enforce this, but ultimately, the politicians, and we the electorate, must demand it.

Ron DeSantis chose his moment with care. The night before the US midterms, the outgoing Governor of Florida appeared on a sports podcast. On election eve, DeSantis admitted that the Iran war had been ‘a big, big drag’ on Republicans, that the party had been ‘gaslighting’ voters by blaming Joe Biden for the price of […]
English rock fans are understandably thrilled over the announcement that Oasis will embark on another tour, including a stop in Manchester, where the band first got started in 1991. And while that may be good news, fans are still going to have a difficult time seeing them perform live – affording it, that is. Live […]
Reports earlier this week suggested that there have been ‘robust cabinet discussions’ over the Government’s approach to AI. The Financial Times reports that those discussions have yielded seven core principles, signed off but not yet published, including that ‘control and sovereignty matter’ and ‘infrastructure must serve a national purpose and deliver for communities’. Missing from […]