Is this Rachel Reeves’s greatest achievement yet?
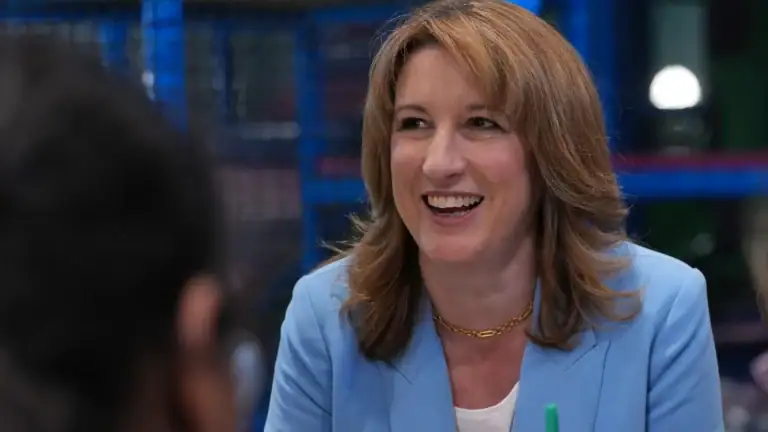
Kin Cheung- WPA Pool/Getty Images
Rachel Reeves probably did not expect regulatory reform of ring-fencing rules to become one of her more significant achievements as Chancellor. But credit where it’s due, the Government is right to pursue serious, common-sense reform of ring-fenced banks (RFBs) in order to free up capital for investment in British businesses.
Since the 2008 Global Financial Crisis, banks have been constrained by layer upon layer of regulation designed to protect customers and restore confidence in the financial system. At the time, this made complete political sense. A country forced to bail out banks that were ‘too big to fail’ was always going to demand a far more cautious regulatory framework in return.
But like the return of Andy Burnham to frontline national politics, the rules on RFBs should be left in the 2010s – they are a hangover from a different era. The cumulative effect of post-crisis regulation has been to suppress risk appetite and reduce lending to higher-risk propositions such as SMEs. Onerous risk-weighted capital requirements force banks to hold back capital in proportion to risk, making productive business lending less attractive.
Ring-fencing forms part of this wider architecture of regulatory bubble wrap imposed on banks after 2008. Under the regime, large UK banks with more than £25 billion in retail deposits must separate core retail banking operations from riskier investment banking activities, in order to shield consumers from exposure to losses arising elsewhere in the group.
Ring-fencing forms part of this wider architecture of regulatory bubble wrap imposed on banks after 2008
While well intentioned, ring-fencing has also produced market distortions and perverse incentives. In practice, it has imposed rigid capital and asset constraints on ring-fenced banks, limiting the amount of capital they can deploy into commercial and business lending. It has restricted the range of financial products they are permitted to offer. A business might, for example, secure a loan from a RFB, but then be forced to approach a separate non-ring-fenced institution for export finance or more sophisticated products – needlessly adding friction and barriers to access to capital.
This framework has helped give rise to challenger banks and alternative lenders seeking to fill the gaps left by traditional institutions. Greater competition and choice in lending markets is welcome. But many of these ‘market failures’ are, in truth, self-inflicted. It is like tying a boxer’s hands behind his back before the match begins, and then celebrating the emergence of a new champion.
The reforms now being discussed represent a genuine paradigm shift. They signal that the UK is finally serious about unpicking some of the more cumbersome elements of its post-2008 banking regime. That should be welcomed.
The Government is consulting on proposals to introduce a ‘New Growth Allowance’ that would permit ring-fenced banks to undertake certain activities currently prohibited under existing rules. This would provide greater flexibility for banks to offer products and services that businesses actually need, while potentially unlocking up to £80bn in additional financing capacity for the UK economy.
This is not comparable in scale to Nigel Lawson’s ‘Big Bang’ reforms, but it is arguably the soundest piece of economic policy this Government has produced so far – and ever will. What is striking is the contradiction at the heart of the wider economic agenda. On the one hand, ministers are acknowledging that excessive state regulation has clogged up the banking system and constrained productive investment; on the other, they continue to flirt with Cuban-style price controls to tackle inflation.
The lesson of ring-fencing reforms is straightforward – markets are not failing because markets themselves are broken, but because the state has overregulated them. That lesson ought to be applied far more broadly across the British economy.
The right language aimed at the wrong level. This was a Budget focused on micro-management. The Chancellor used the right language about the need to help workers and business, but it was predicated on ‘the state knows best’, with significant interference through targeted spending and tax hikes. The Red Book contained no fewer than 98 […]
Imagine borrowing £10,000 from the bank, lending it to a friend, then telling everyone the debt’s gone – because your friend owes you the money. That’s obviously nonsensical – you still owe the same £10,000 to the bank, regardless of what you did with the money. But that’s Labour’s approach to our public finances. Let […]
When John Healey sits down next Wednesday, the press gallery will focus hard on his headroom against the fiscal rules. In March the OBR put this at £23.6 billion against the main rule, which requires day-to-day spending to be covered by revenue by 2029/30. A recent Reuters poll of economists suggests it has since shrunk […]